Final 2023 interconnections (17.6 GWac – up 60% y/y); 2024 will surge again
This week, the EIA released final December and 2023 interconnection data, highlighting 5.6 GWac turned on in December alone.
SOLARSAT™: Activity still chugging along nicely
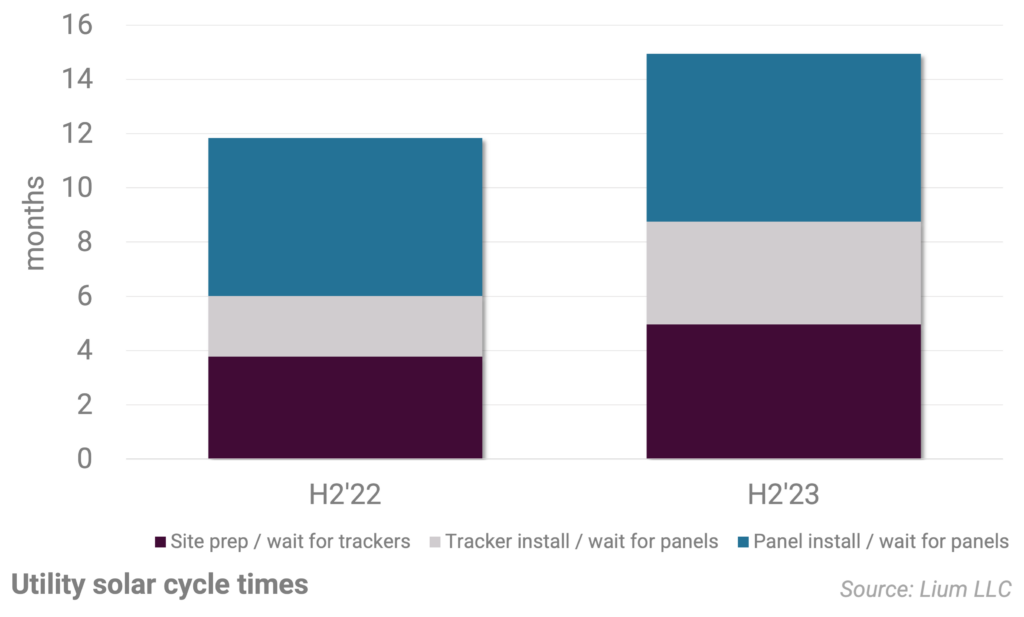
Generally speaking, activity has continued to chug along in recent months despite fears from some public companies that developers are delaying work (ie ARRY, MTZ).
2024 Outlook – Interconnections surge again (50% above Woodmac estimates); New construction +15-20%
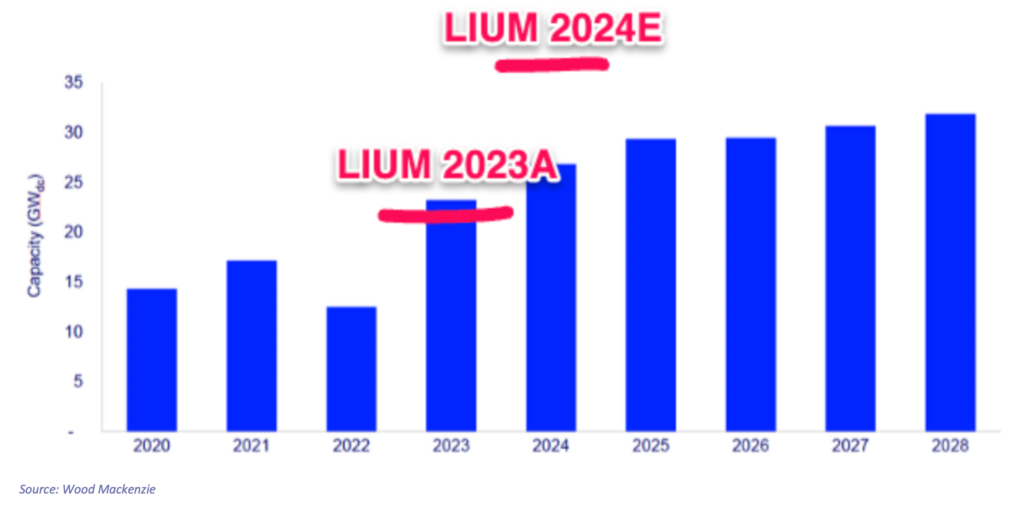
In this note, we are updating our utility solar model (LS-1), highlighting forecasts for interconnections, new construction, trackers, and panel installations.
4Q Pipeline Update (still growing after another 11 GWac originations); NXT/PWR/SOLV/PRIM most leverage
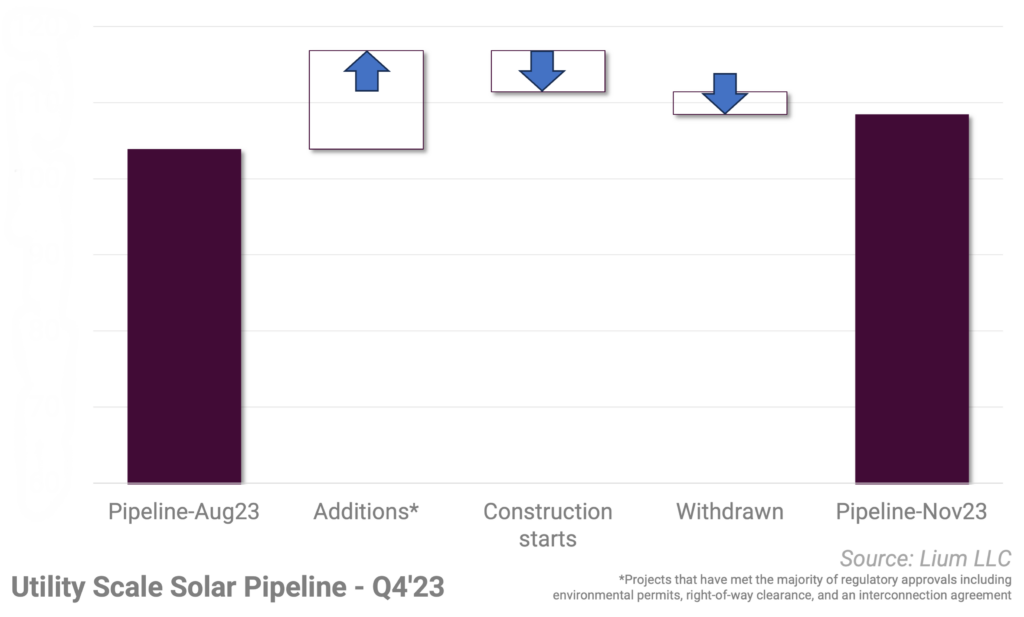
In this note, we are updating our list of of U.S. utility scale solar projects that are in the late stage development pipeline (defined as regulatory hurdles cleared such as environmental siting, right-of-way clearance, interconnection agreement).
SOLARSAT™: November new construction slowing for the winter
During November we counted roughly 1.7 GWac of projects that kicked off during the month.
SOLARSAT™: October new construction still firm (up >20% y/y)
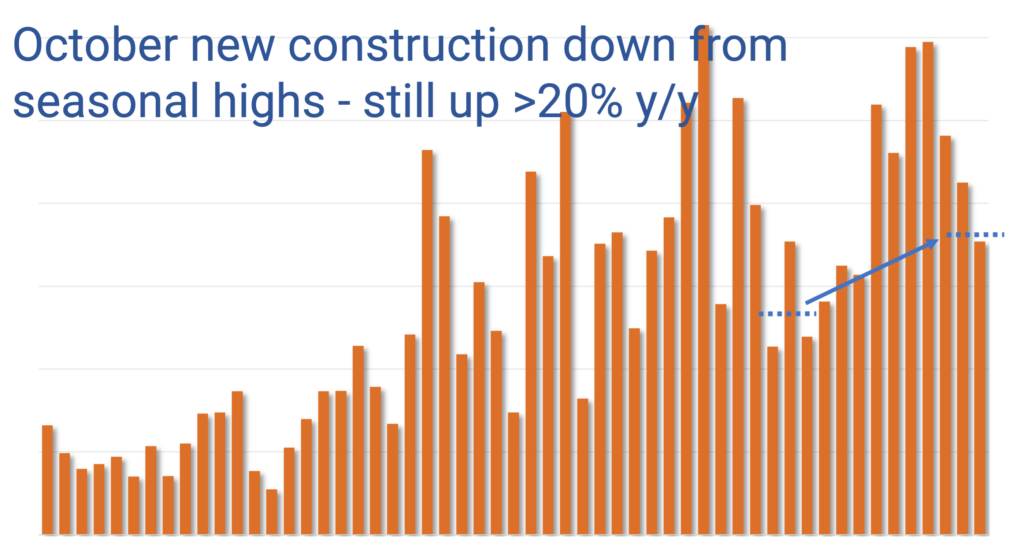
One of the constants we have found in utility scale solar development is that ALL projects experience delays
SOLARSAT™: If developers are going to slow down, they haven’t yet (September new construction up 25% y/y)
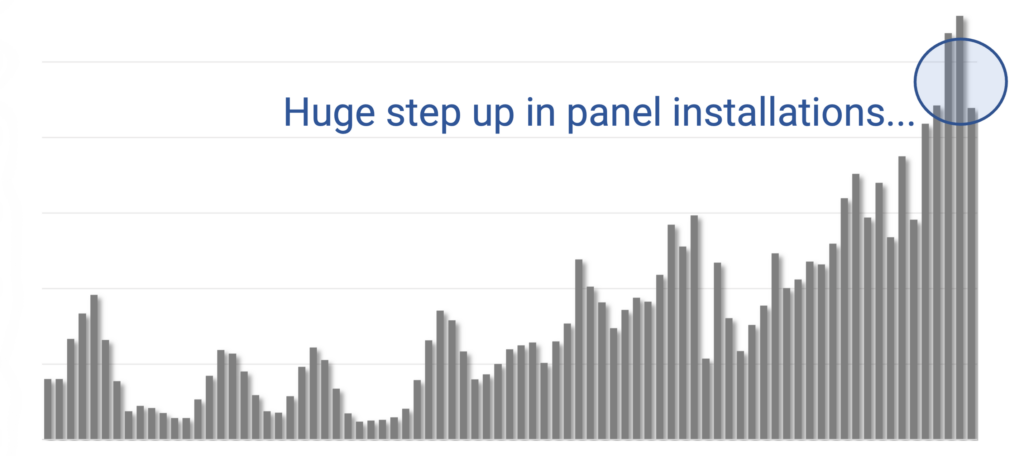
More than 2 GWac of projects were started in September, down from 3 GWac in June / July, but still up 25% from a year ago.
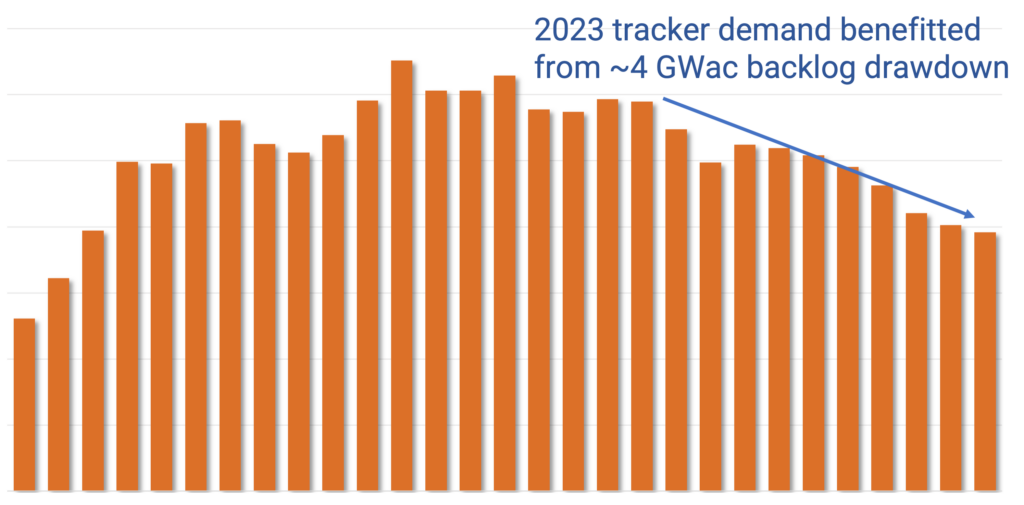
SOLARSAT™: Utility Solar full steam ahead; Q3 tracking +20% y/y; Panel installs up 2x; ARRY slow
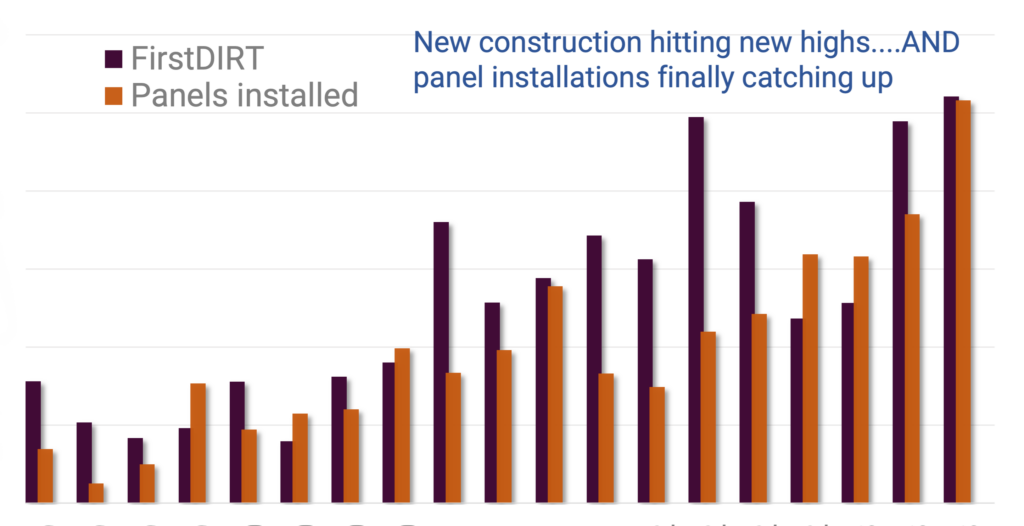
Assuming the industry continues to click, the U.S. will soon be installing 30-40 GWac (40-50 GWdc) of utility solar per year
SOLARSAT™: July hitting on all cylinders
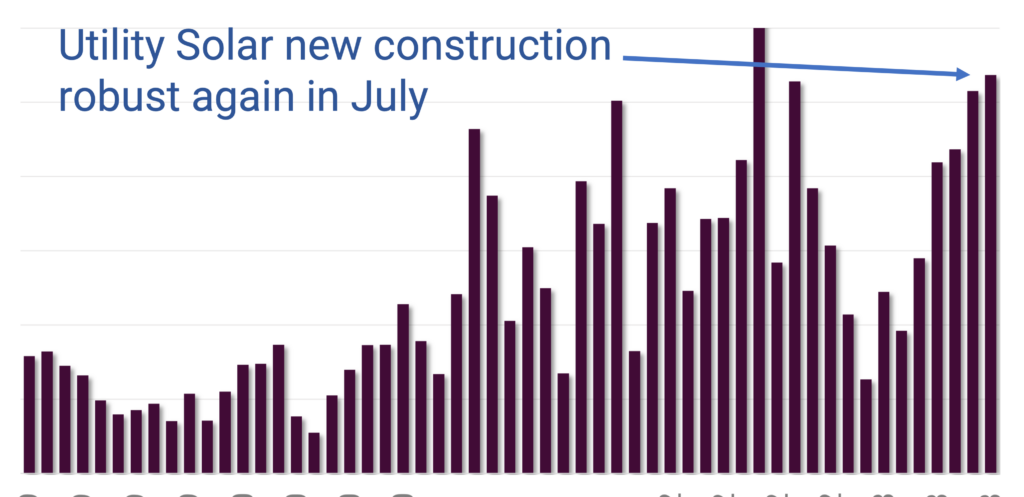
Broadly speaking, activity across the board was robust in July, particularly for new construction which was almost double last year.
SOLARSAT™: June BIG month for new construction starts
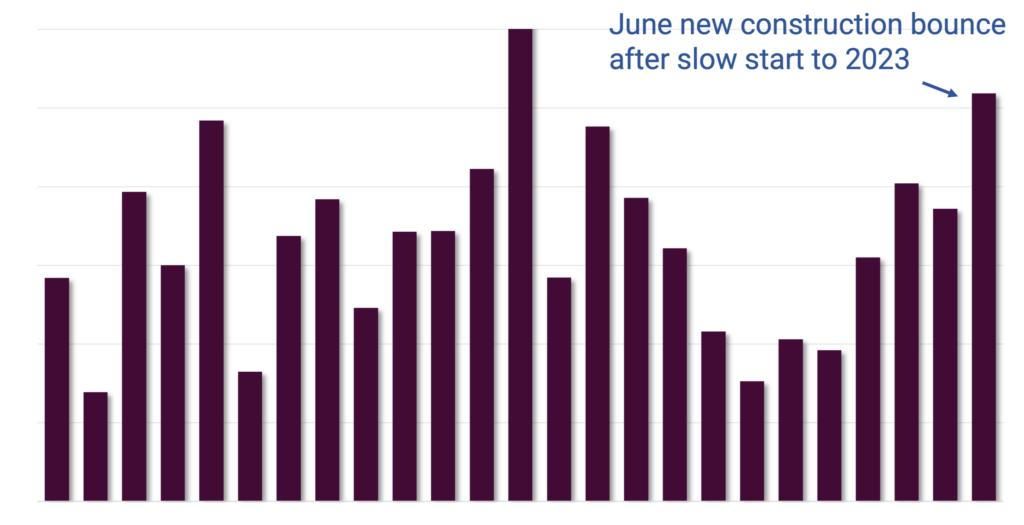
roughly 2.5 GWac (30 GW annually) of new solar was started in June, suggesting that tracker demand can continue to grow despite mediocre new construction in early 2023